
Selling on credit is one of the fastest ways to win customers, and one of the fastest ways to run out of cash. The difference usually comes down to a single document: a written credit policy. It tells your team who can buy on account, how much they can owe, when they must pay, and what happens if they do not.
Writing one from scratch takes time. The free credit policy templates below give you a working structure that you can adapt to your own business in an afternoon.
What a Credit Policy Actually Does
Think of it as the rulebook for your accounts receivable. A clear policy means two sales reps will make the same decision about the same customer. It speeds up approvals for good customers, protects you from risky ones, and gives your finance team a fair, consistent basis for chasing late payments.
The Main Sections of a Credit Policy
- Purpose and scope – who the policy applies to and who owns it.
- Credit application – the information new customers must provide, usually including two or three trade references (see our trade reference templates).
- Credit limits – how limits are set, reviewed and raised.
- Payment terms – for example net 30, early-payment discounts and accepted payment methods.
- Collections – reminder schedule, late fees, account holds and when a debt goes to collection.
- Approval levels – who can approve what amount.
- Review – how often the policy itself is updated.
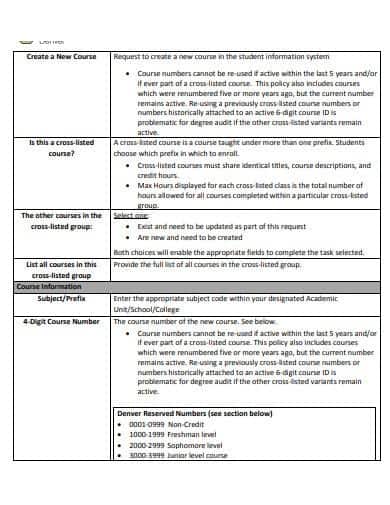
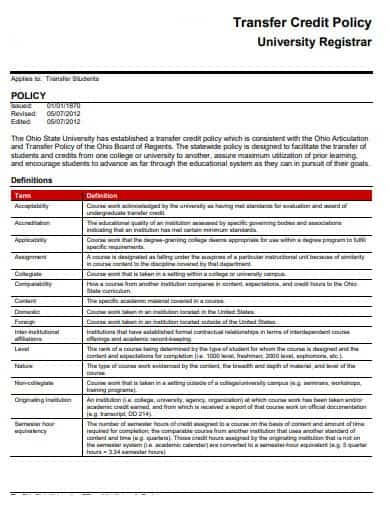
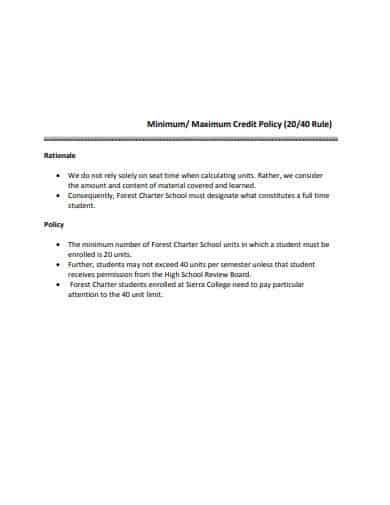
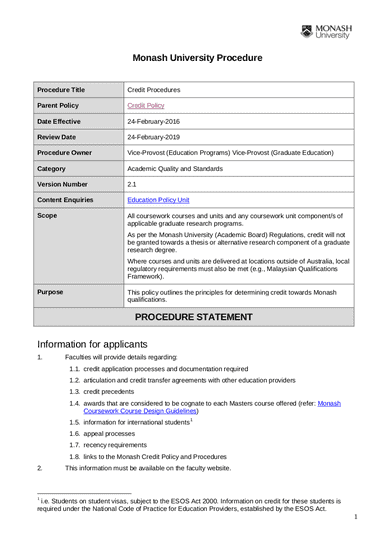
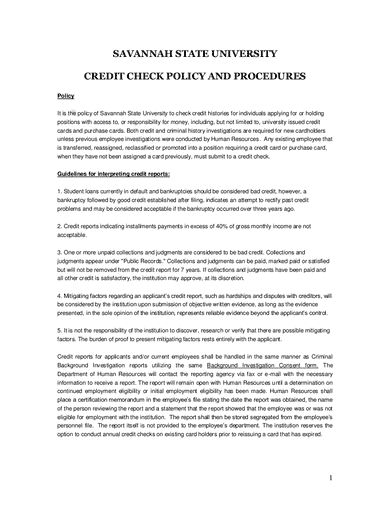
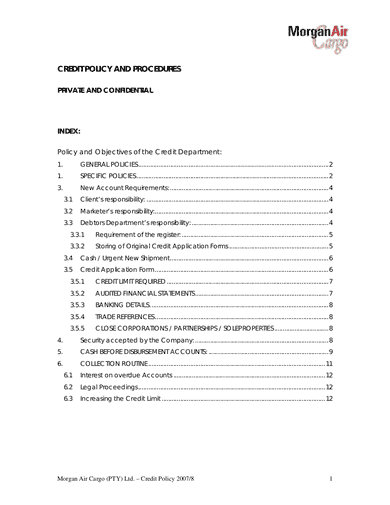
Download Credit Policy Templates


Making the Policy Work Day to Day
A policy only helps if people follow it. Share a one-page summary with your sales team, print the payment terms on every invoice, and review overdue accounts every week rather than every quarter. When a good customer hits a rough patch, offering a written payment plan agreement often recovers more money than a demand letter.
Setting up other policies for your company? You may also find our quality assurance policy templates and refund policy templates useful.
Frequently Asked Questions
What is a credit policy?
It is a written set of rules that explains how a business grants credit to customers, sets limits and payment terms, and collects overdue payments.
Do small businesses need a credit policy?
Yes, arguably more than large ones. A few unpaid invoices can hurt a small business badly, and a simple policy helps prevent that.
What are typical payment terms?
Net 30 is the most common, meaning payment is due 30 days after the invoice date. Net 15 and net 60 are also widely used.
How often should a credit policy be reviewed?
Once a year is a good rule, or sooner if your customer base, cash position or the wider economy changes significantly.

You must be logged in to post a comment.